


By Bret Butler | Butler & Butler at Compass | Founding Broker, Compass Washington | Last updated: November 10, 2026
Should you sell your home before buying the next one? If you’re moving up or downsizing in Woodinville, Redmond or elsewhere on the Eastside, the right answer depends on your equity, your financing and your timing. Selling first is generally the safer choice when you need the proceeds for your next down payment. Buying first can make sense if you’re comfortable carrying both homes or can arrange bridge financing. At Butler & Butler at Compass, we help you weigh both approaches using current local market data and a plan that fits your situation.
I’m Bret Butler. Our family team at Butler & Butler at Compass includes Lisa, Greg and Sunny Butler. We bring 41 years of experience and over 100 years of combined experience helping Eastside buyers and sellers. We’re ranked #1 in Woodinville and #24 in Washington by sales volume (RealTrends Verified 2026, 2025 sales data). This guide builds on our buy before you sell pros and cons and takes a closer look at the current market, your financing options and how to coordinate a move involving $1M–$2M homes.

Key numbers: selling and buying on the Eastside (checked November 10, 2026)
- Eastside single-family homes (NWMLS, October 2026): 1,764 for sale (up 48.11% from a year earlier); median sale price $1,350,000 (down 12.90%); 4.32 months of inventory
- Woodinville (Redfin, three months ending October 2026): median sale price $1,274,114 (up 8.7%); median 19 days on market
- Redmond (Redfin, same period): median sale price $1,174,183 (down 11.5%); median 40 days on market
- Offers contingent on selling a previous home: 30% of buyers in 2026, up from 21% in 2025 (Zillow, October 14, 2026)
- 30-year fixed mortgage average: 7.18% on November 5, 2026; 6.22% a year earlier (Freddie Mac PMMS)
- Bridge loan: a temporary loan with a term of 12 months or less (CFPB Regulation Z)
- 2027 state REET: 2.75% on the part of a sale price above $1,551,000 up to $3,051,000 (Washington Department of Revenue)
Should you sell first or buy first on the Eastside right now?
The first thing I ask clients is whether they need the equity from their current home to purchase the next one. That usually tells us which direction makes the most sense. If you need those proceeds, selling first or borrowing against your equity becomes part of the plan. If you don’t, we can look at buying first and determine how much financial overlap you’re comfortable with.
There are advantages to both approaches in the current Eastside market. According to NWMLS, there were 1,764 single-family homes for sale at the end of October 2026, up 48.11% from a year earlier. The median sale price was $1,350,000, down 12.90%. Buyers have more homes to choose from, which can make finding your next property easier. For sellers, the additional inventory means we need to be realistic about pricing and how long a sale could take.
That timing can look very different depending on where you live. According to Redfin, Woodinville homes spent a median of 19 days on the market during the three months ending October 2026. In Redmond, the median was 40 days. If you’re selling in Redmond and buying first, we need to account for the possibility of carrying both properties longer.
| City | Median sale price | Change from a year earlier | Median days on market (a year earlier) |
|---|---|---|---|
| Woodinville | $1,274,114 | +8.7% | 19 (22) |
| Redmond | $1,174,183 | -11.5% | 40 (35) |
| Kirkland | $1,191,671 | -8.3% | 31 (22) |
| Sammamish | $1,424,009 | -9.59% | 36 (30) |
| Bellevue | $1,446,854 | -4.8% | 31 (17) |
The local inventory numbers reinforce why planning matters. NWMLS area 600 (Woodinville and Juanita) had 444 single-family homes for sale at the end of October 2026 compared with 290 a year earlier. Area 550 (Redmond and Carnation) had 4.23 months of inventory, according to the NWMLS October 2026 breakouts. These are important considerations when deciding whether to sell first or take on the risk of owning both homes. You can also explore our Redmond guide, Kirkland market update and Bellevue buyer guide for more local information.
What are your options for selling and buying at the same time?
There isn’t one approach that works for everyone. Depending on your finances, the home you’re selling and the property you want to purchase, there are several ways to structure the move. These are the five options we typically consider.
| Option | How it works | Best for | Main risk | Costs to plan for |
|---|---|---|---|---|
| Sell first | Close on your current home, then use the proceeds to purchase the next one | Sellers who need their equity for the next down payment | You may need temporary housing if your next home isn’t ready | Moving twice and short-term housing |
| Buy first with a bridge loan or HELOC | Use your current home’s equity to purchase, then repay the financing when it sells | Sellers who qualify to carry both payments | Your current home may take longer to sell than expected | Loan interest, fees and overlapping payments |
| Buy with a home sale contingency | Make your purchase dependent on selling your current home by an agreed date | Buyers whose home is already listed or under contract | The seller may decline your offer or accept a stronger one | Potentially less flexibility when negotiating price and terms |
| Sell with a rent-back or later closing | Close your sale but arrange to remain in the home temporarily | Sellers who want the certainty of a sale without moving twice | The buyer’s lender may restrict the occupancy period | Negotiated rent or an adjustment to the sale price |
| Back-to-back closings | Coordinate your sale to close just ahead of your purchase | Sellers with a committed buyer and flexibility on their next purchase | A delay with either transaction can affect both closings | Limited additional expense but careful coordination is needed |
Will an Eastside seller accept an offer that depends on selling your home?
Yes. These offers are becoming more common. According to Zillow’s 2026 Consumer Housing Trends Report, published October 14, 2026, 30% of buyers reported that their final offer was contingent on selling their previous home. That’s up from 21% in 2025.
With less competition, some sellers may be more willing to consider a contingent offer. Nationally, homes received an average of 2.2 offers in September 2026 compared with 2.3 a year earlier, according to the NAR REALTORS Confidence Index. That doesn’t mean every seller will accept one. They may want to keep marketing their property and require you to remove your contingency within a short period if another offer comes in. Having your current home already listed or under contract can make your offer much more appealing.
How do bridge loans and HELOCs let you buy before you sell?
If you’ve found the right home but haven’t sold your current property, bridge financing may give you another option. A bridge loan allows you to borrow against your existing equity to help purchase the next home. Under CFPB Regulation Z, 12 CFR 1026.43, a bridge loan is described as temporary financing with a term of 12 months or less, including situations where you’re buying a new home and expect to sell your current one within 12 months.
A home equity line of credit (HELOC) is another way to access that equity. There are important differences to understand. The CFPB’s HELOC guide explains that variable interest rates can change your payment even without additional borrowing. Lenders can also generally freeze or reduce the available credit if your property’s value declines. I recommend having this conversation with your lender before your home goes on the market, not after you’ve found something you want to buy.
Bridge loan rates and costs depend on the lender and your financial situation. Compare written terms from two or three lenders, including the interest rate, fees and repayment period. The 2026 conforming loan limit for a one-unit home in King County is $1,063,750, according to FHFA. Because many $1M–$2M purchases involve jumbo financing, it’s important to understand how your lender will evaluate both mortgage payments.
Preparing your current home for sale is another part of the equation. If improvements are needed, Compass Concierge can help cover upfront preparation expenses such as painting and staging, with zero due until closing (loans from Notable Finance, LLC; approval not guaranteed).
Can you sell first and stay in your home with a rent-back?
Absolutely, provided the buyer agrees. A rent-back, also called a post-closing occupancy agreement, allows you to complete the sale of your current home while remaining there temporarily. This can give you time to close on your next purchase without having to move twice. The agreement should clearly address rent, the deposit, utilities and your move-out date.
The buyer’s financing is an important consideration. In Zillow’s 2026 survey, 77% of buyers used a mortgage. Under Fannie Mae’s Selling Guide, a principal residence is a property the borrower occupies within 60 days after closing. That means the rent-back needs to work within the buyer’s lender requirements. If you need more flexibility, negotiating a later closing date may be a better solution.
How do you time two closings without moving twice?
Coordinating back-to-back closings is possible, but it takes preparation. The goal is to close the sale of your current home just before your next purchase, allowing the proceeds to be available when you need them. Nationally, contracts typically closed in 30 days in September 2026, according to NAR. However, 16% of contracts experienced delayed settlements over the prior three months. We need to plan for that possibility rather than assume everything will happen exactly on schedule.
- Prepare your home first. Have the property ready for market and establish a realistic pricing strategy before making an offer on the next home.
- Match the dates. Whenever possible, schedule your current sale to close a day or more before your purchase.
- Plan the money trail. Confirm with escrow when your sale proceeds will be available for the next transaction.
- Have a fallback. Consider negotiating a short rent-back or the ability to extend closing if something gets delayed.
We work directly with both escrow officers and both lenders to keep the transactions coordinated. If you’d like to understand what happens once you’re under contract, our guide to what happens after accepting an offer walks through the process.
What do REET and capital gains mean when you sell and buy?
When you’re calculating how much equity you’ll have available for your next purchase, it’s important to account for selling costs and taxes. In Washington, the seller pays real estate excise tax (REET) under RCW 82.45.080. New state tiers take effect January 1, 2027: 1.1% up to $551,000, 1.28% to $1,551,000, 2.75% to $3,051,000 and 3.0% above that, plus the local rate, according to the Washington Department of Revenue. For a $1,750,000 sale closing in 2027, the state portion would be about $24,334 compared with about $24,763 under the 2026 tiers. Our Washington REET 2027 guide explains the local rates in more detail.
Capital gains are another consideration, particularly if you’ve owned your home for a long time. Under IRS rules, qualifying homeowners may exclude up to $250,000 of gain from the sale of their primary residence ($500,000 for married couples filing jointly) if they’ve owned and lived in the home for at least 24 months of the last five years. Generally, you can’t claim the exclusion if you’ve used it for another property within the prior two years. Washington’s capital gains tax does not apply to real estate sales under RCW 82.87.050.
I recommend reviewing your specific tax situation with your CPA before committing to a timeline. You can also read our guide to the hidden costs of selling a home in Washington to better understand the expenses involved.
What should buyers know when the seller also has to buy?
If you’re purchasing a home from someone who is also planning their next move, understanding their timing can help you put together a stronger offer. A short rent-back or a closing date that works with their next purchase may be just as important to them as other terms.
If you’re the buyer who also needs to sell, preparation is equally important. Having your home listed or ready to go on the market can make a contingent offer more attractive. We also need to be realistic about the timeline. Woodinville’s median of 19 days on market is quite different from Redmond’s 40 days. Your contingency should reflect the market where you’re selling.
Financing needs to be part of the conversation as well. According to Freddie Mac PMMS, the average 30-year fixed mortgage rate was 7.18% on November 5, 2026 compared with 6.22% a year earlier. Before buying first, have your lender calculate what carrying both properties would look like so you know the financial commitment.
How does Butler & Butler help Eastside sellers plan both moves?
When we’re helping a client sell one home and purchase another, I believe both transactions need to be planned together from the beginning. We look at what your current home is likely to sell for, how long it may take in today’s market and what financing options are available before you commit to the next purchase. From there, we develop a pricing and marketing strategy that supports your overall move. You can learn more about our approach on our Butler Difference and Sell Your Home pages.
Here are some of our recent sales nearest the $1M–$2M range:
| Address | Sale price | Closed | We represented |
|---|---|---|---|
| 7120 259th Pl NE, Redmond 98053 | $2,695,000 | October 2026 | Sellers |
| NE 129th Way, Woodinville 98077 | $2,175,000 | October 2026 | Buyers |
| 17913 NE 143rd Pl, Woodinville 98072 | $2,300,000 | September 2026 | Sellers and buyers |
| 12426 205th Pl NE, Woodinville 98077 | $2,675,000 | July 2026 | Sellers |
| 16225 NE 112th Ct, Redmond 98052 | $2,160,000 | May 2026 | Sellers |

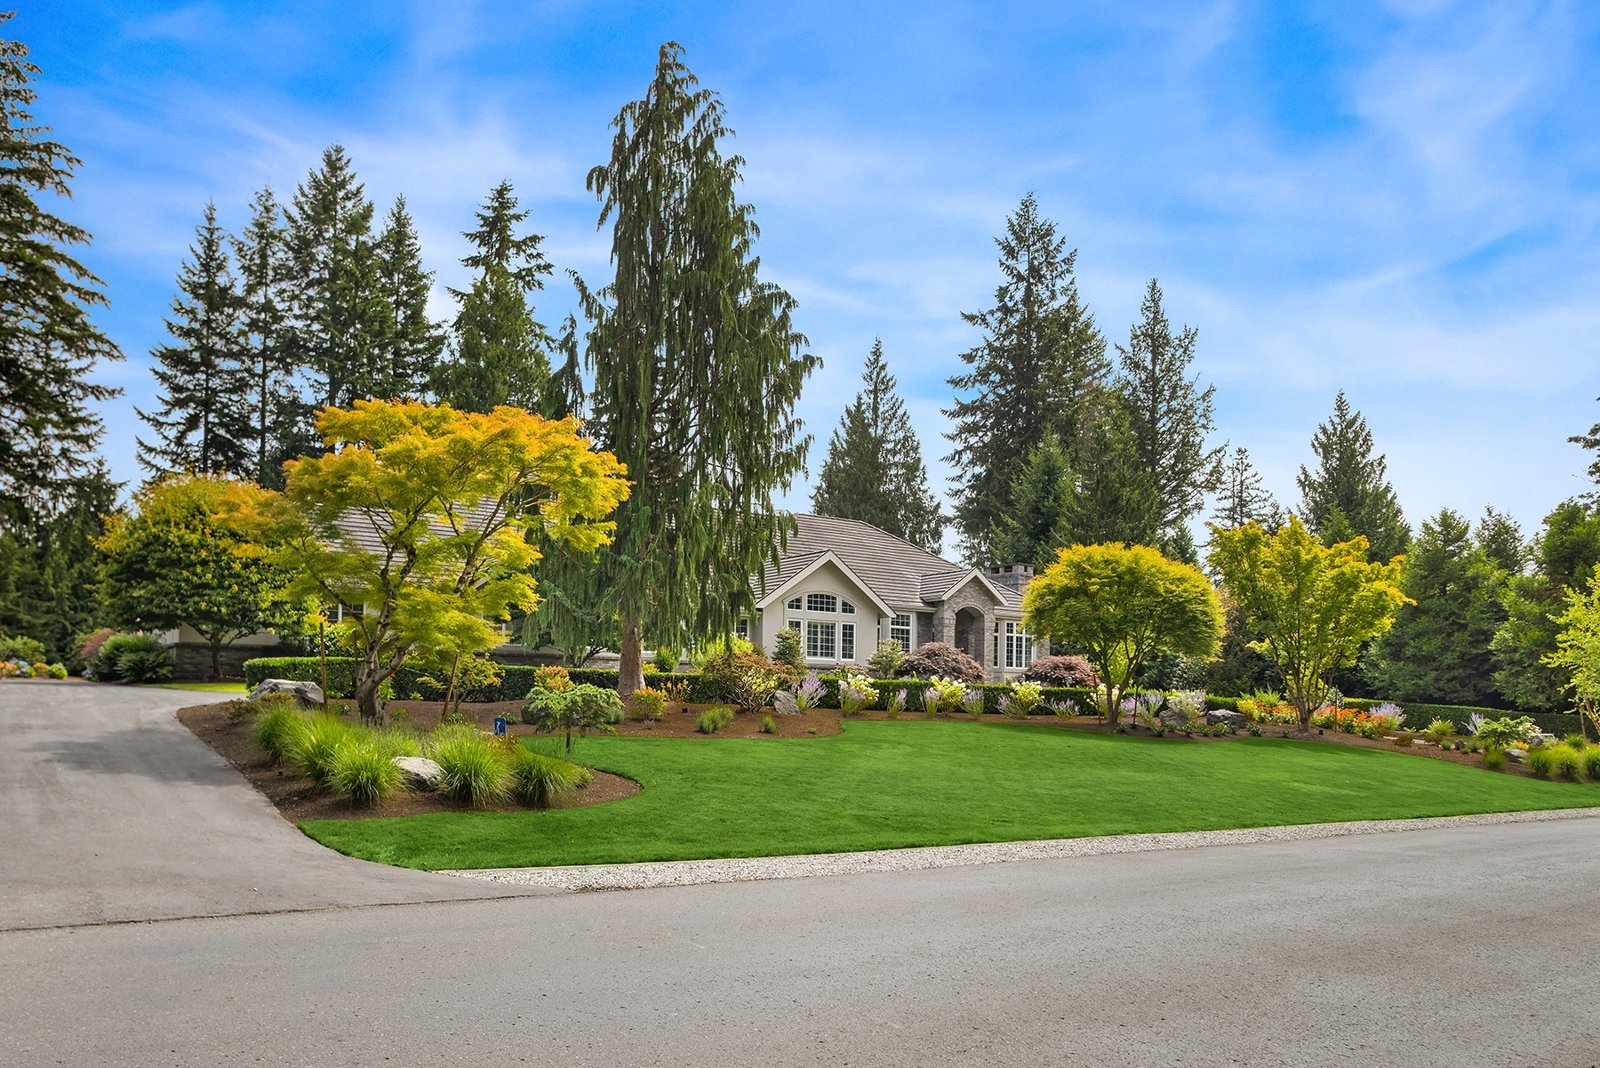
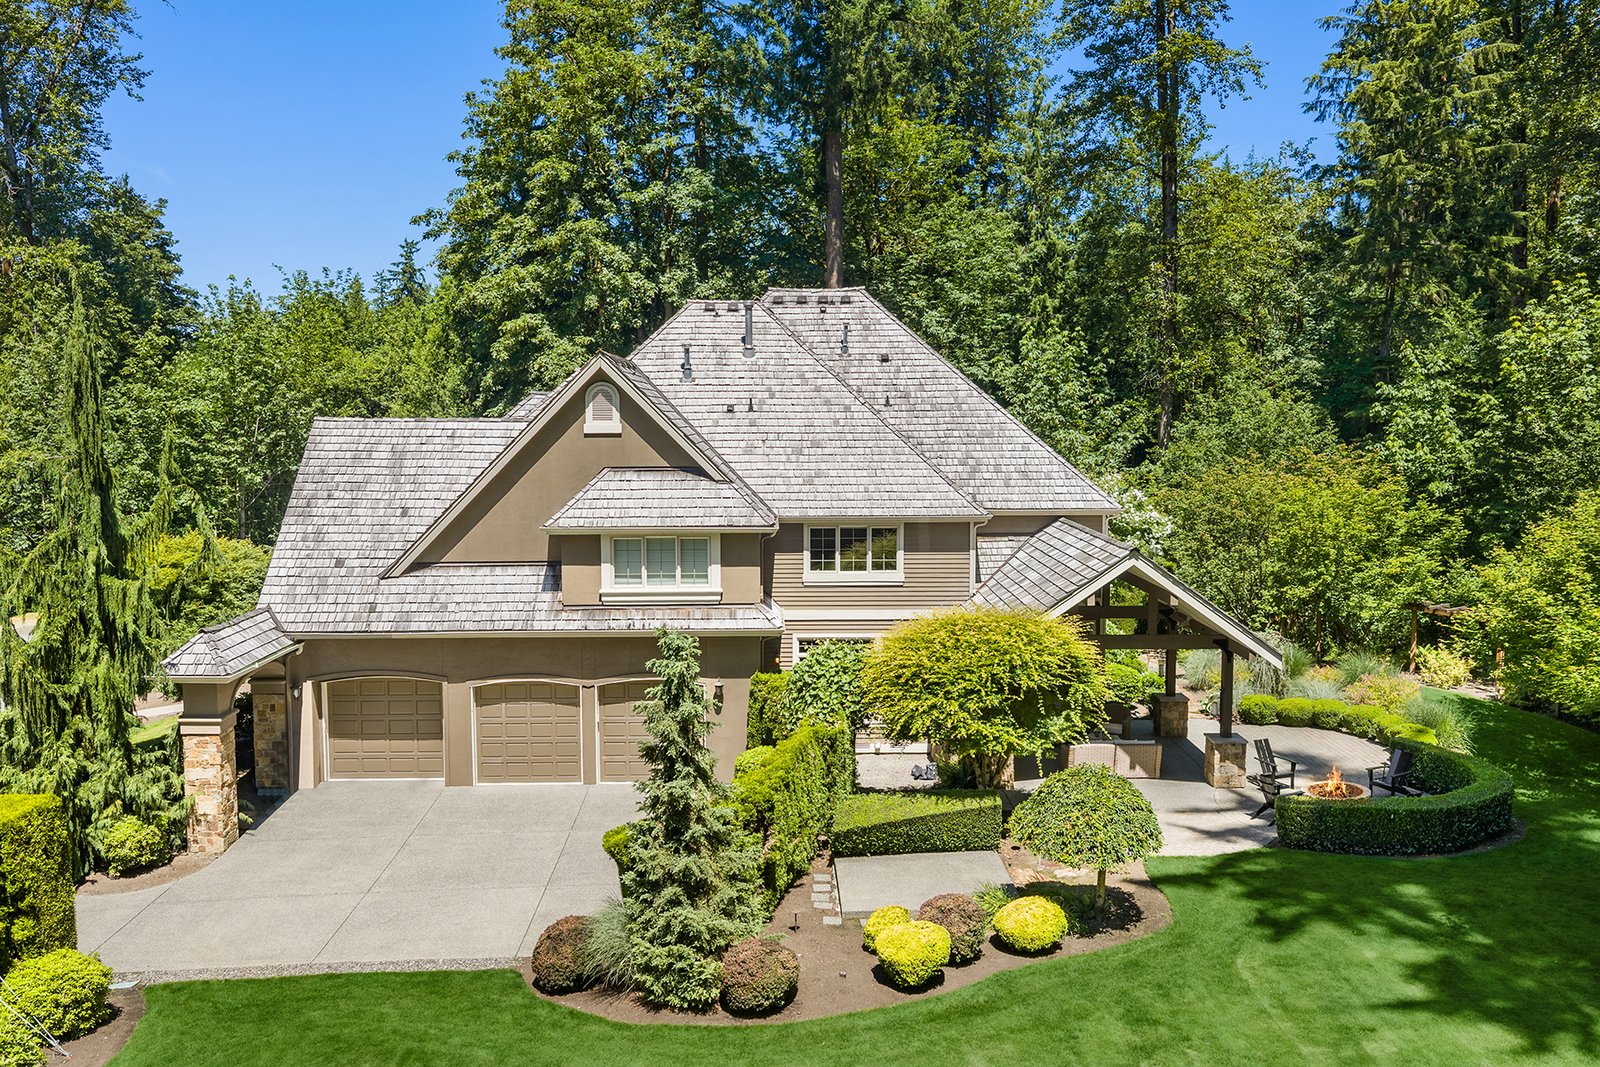
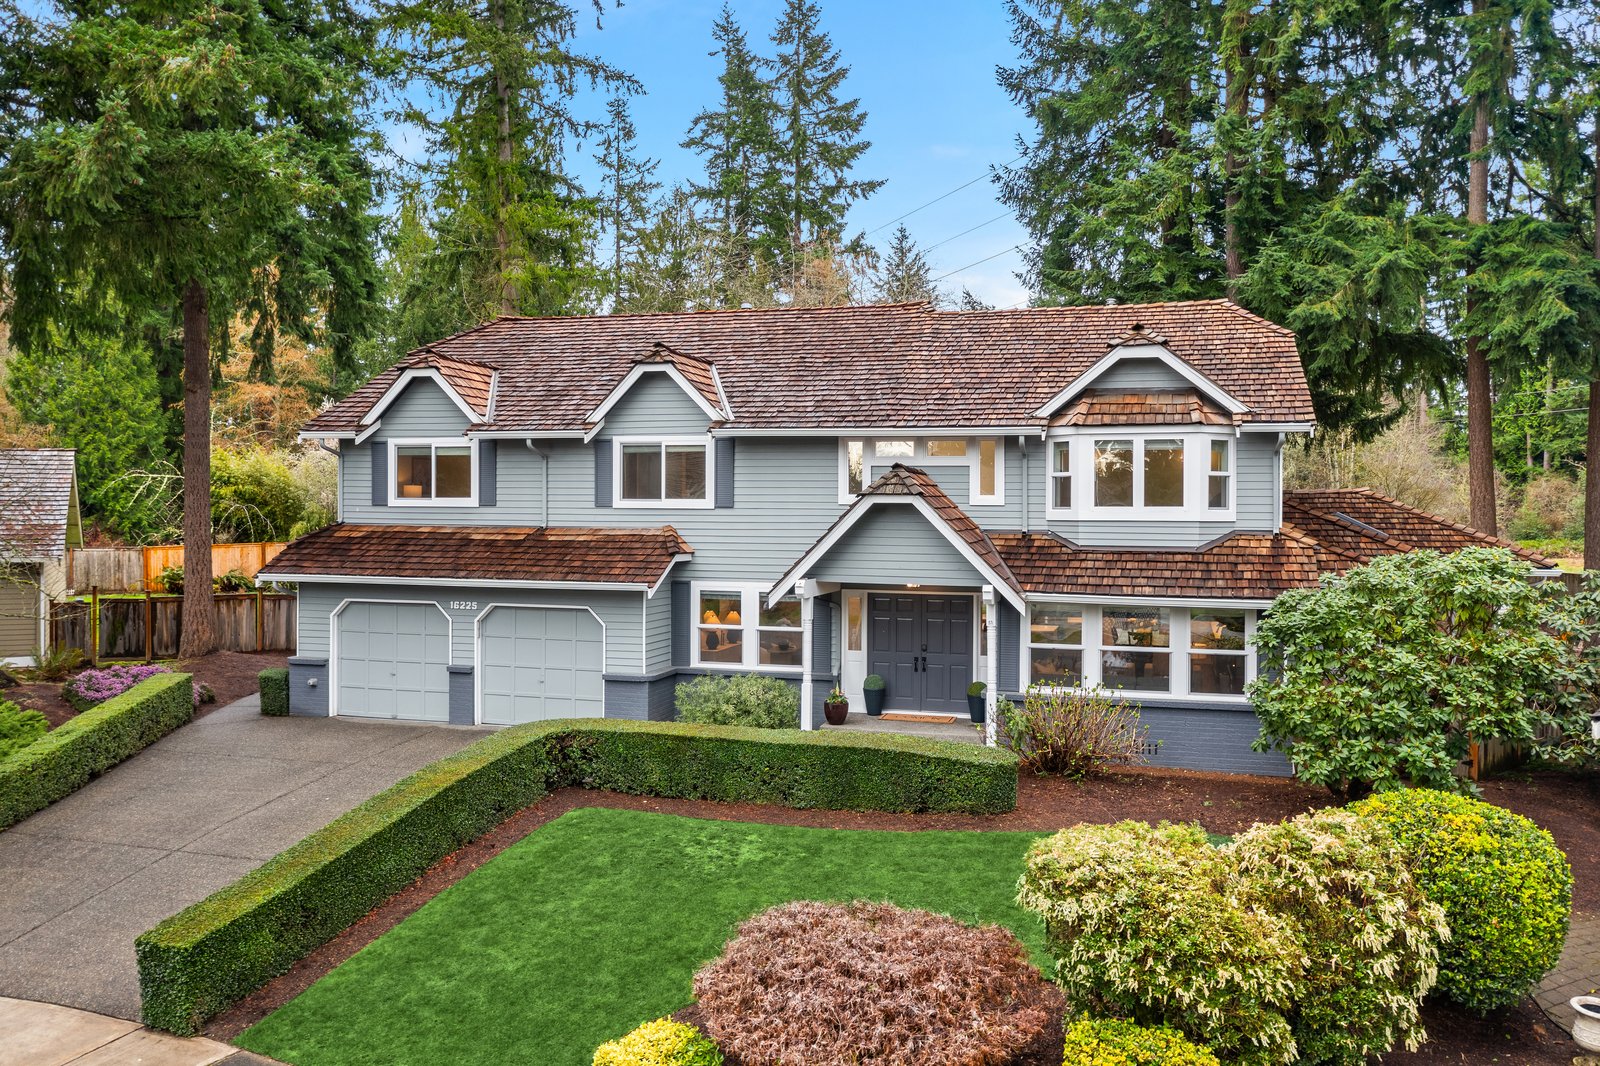
We also have homes available near this range, including 9463 221st Pl NE in Redmond Ridge (98053) at $1,998,000 with 4 bedrooms and 4,165 square feet, 22007 NE 140th Way in Woodinville (98077) at $2,100,000 and 18138 NE 130th Pl in Redmond (98052) at $2,189,000 (Compass, active as of November 10, 2026). You can see our current listings on Bret’s Compass profile.
Frequently asked questions about selling your home before buying
Is it better to sell your home before buying another on the Eastside?
It comes down to your equity and financial flexibility. If you need the proceeds from your current home for the next down payment, selling first is usually the more predictable approach. A rent-back can help with the transition. If you qualify to carry both properties or have access to bridge financing, buying first may allow you to move directly into your next home.
How common are contingent offers in 2026?
They’re becoming more common. Zillow’s 2026 Consumer Housing Trends Report found that 30% of buyers made a final offer contingent on selling their previous home, compared with 21% in 2025. Whether a seller will accept one still depends on the property and the terms of your offer.
What is a bridge loan and how long does it last?
A bridge loan is temporary financing that allows you to use the equity in your current home toward purchasing another. CFPB Regulation Z describes a bridge loan as having a term of 12 months or less. Interest rates, fees and qualification requirements depend on the lender.
How long can a seller rent back after closing?
That depends on what the buyer agrees to and what their lender allows. Fannie Mae defines a principal residence as a property the borrower occupies within 60 days after closing. For financed purchases, the rent-back needs to fit those occupancy requirements. Negotiating a later closing date may provide another option.
Do I pay capital gains tax when I sell my home in Washington?
Washington’s capital gains tax does not apply to real estate sales under RCW 82.87.050. Federal rules may allow you to exclude up to $250,000 of gain on your primary residence ($500,000 for married couples filing jointly) provided you meet the IRS ownership and use requirements.
Who can help me sell my home before buying on the Eastside?
Butler & Butler at Compass is our family real estate team of Bret, Lisa, Greg and Sunny Butler. With 41 years of experience and over 100 years of combined experience, we help buyers and sellers throughout Woodinville, Redmond and the Eastside coordinate both sides of their move. You can reach me directly at 206.604.3350 or Bret@ButlerRealEstate.com.
What is your home worth before you decide?
Before deciding whether to sell first or buy first, the most important place to start is understanding what your current home could sell for in today’s market. That gives us a clearer picture of your available equity, your purchasing options and a realistic timeline for both transactions. You can get a free home valuation and we’ll work through both scenarios together. Feel free to call me directly at 206.604.3350, email Bret@ButlerRealEstate.com or contact us. We’re always happy to help you put together a plan that makes sense for your next move.
Sources (checked November 10, 2026): NWMLS Breakouts: King Map Areas, October 2026 (single-family); Redfin housing market pages for Woodinville, Redmond, Kirkland, Sammamish and Bellevue (three months ending October 2026); Zillow Research Consumer Housing Trends Report 2026 (October 14, 2026); NAR REALTORS Confidence Index, September 2026; Freddie Mac PMMS (November 5, 2026); CFPB Regulation Z (12 CFR 1026.43) and CFPB HELOC guide; Fannie Mae Selling Guide B2-1.1-01; FHFA 2026 conforming loan limits; Washington Department of Revenue; RCW 82.45.080 and 82.87.050; IRS Topic 701; Compass Concierge terms; Compass sale records and King County excise records for our sales. Deemed reliable but not guaranteed. This is general information, not legal, tax or lending advice.
“`
Thinking about selling? See how we help Eastside homeowners sell, or learn about selling in Woodinville and find out what your home is worth.